03 / PORTFOLIO RESEARCH PLATFORM
MarketLab
Every result has a paper trail. Portfolio planning and historical research with validated prices, exact accounting, immutable inputs, and independent calculation checks.
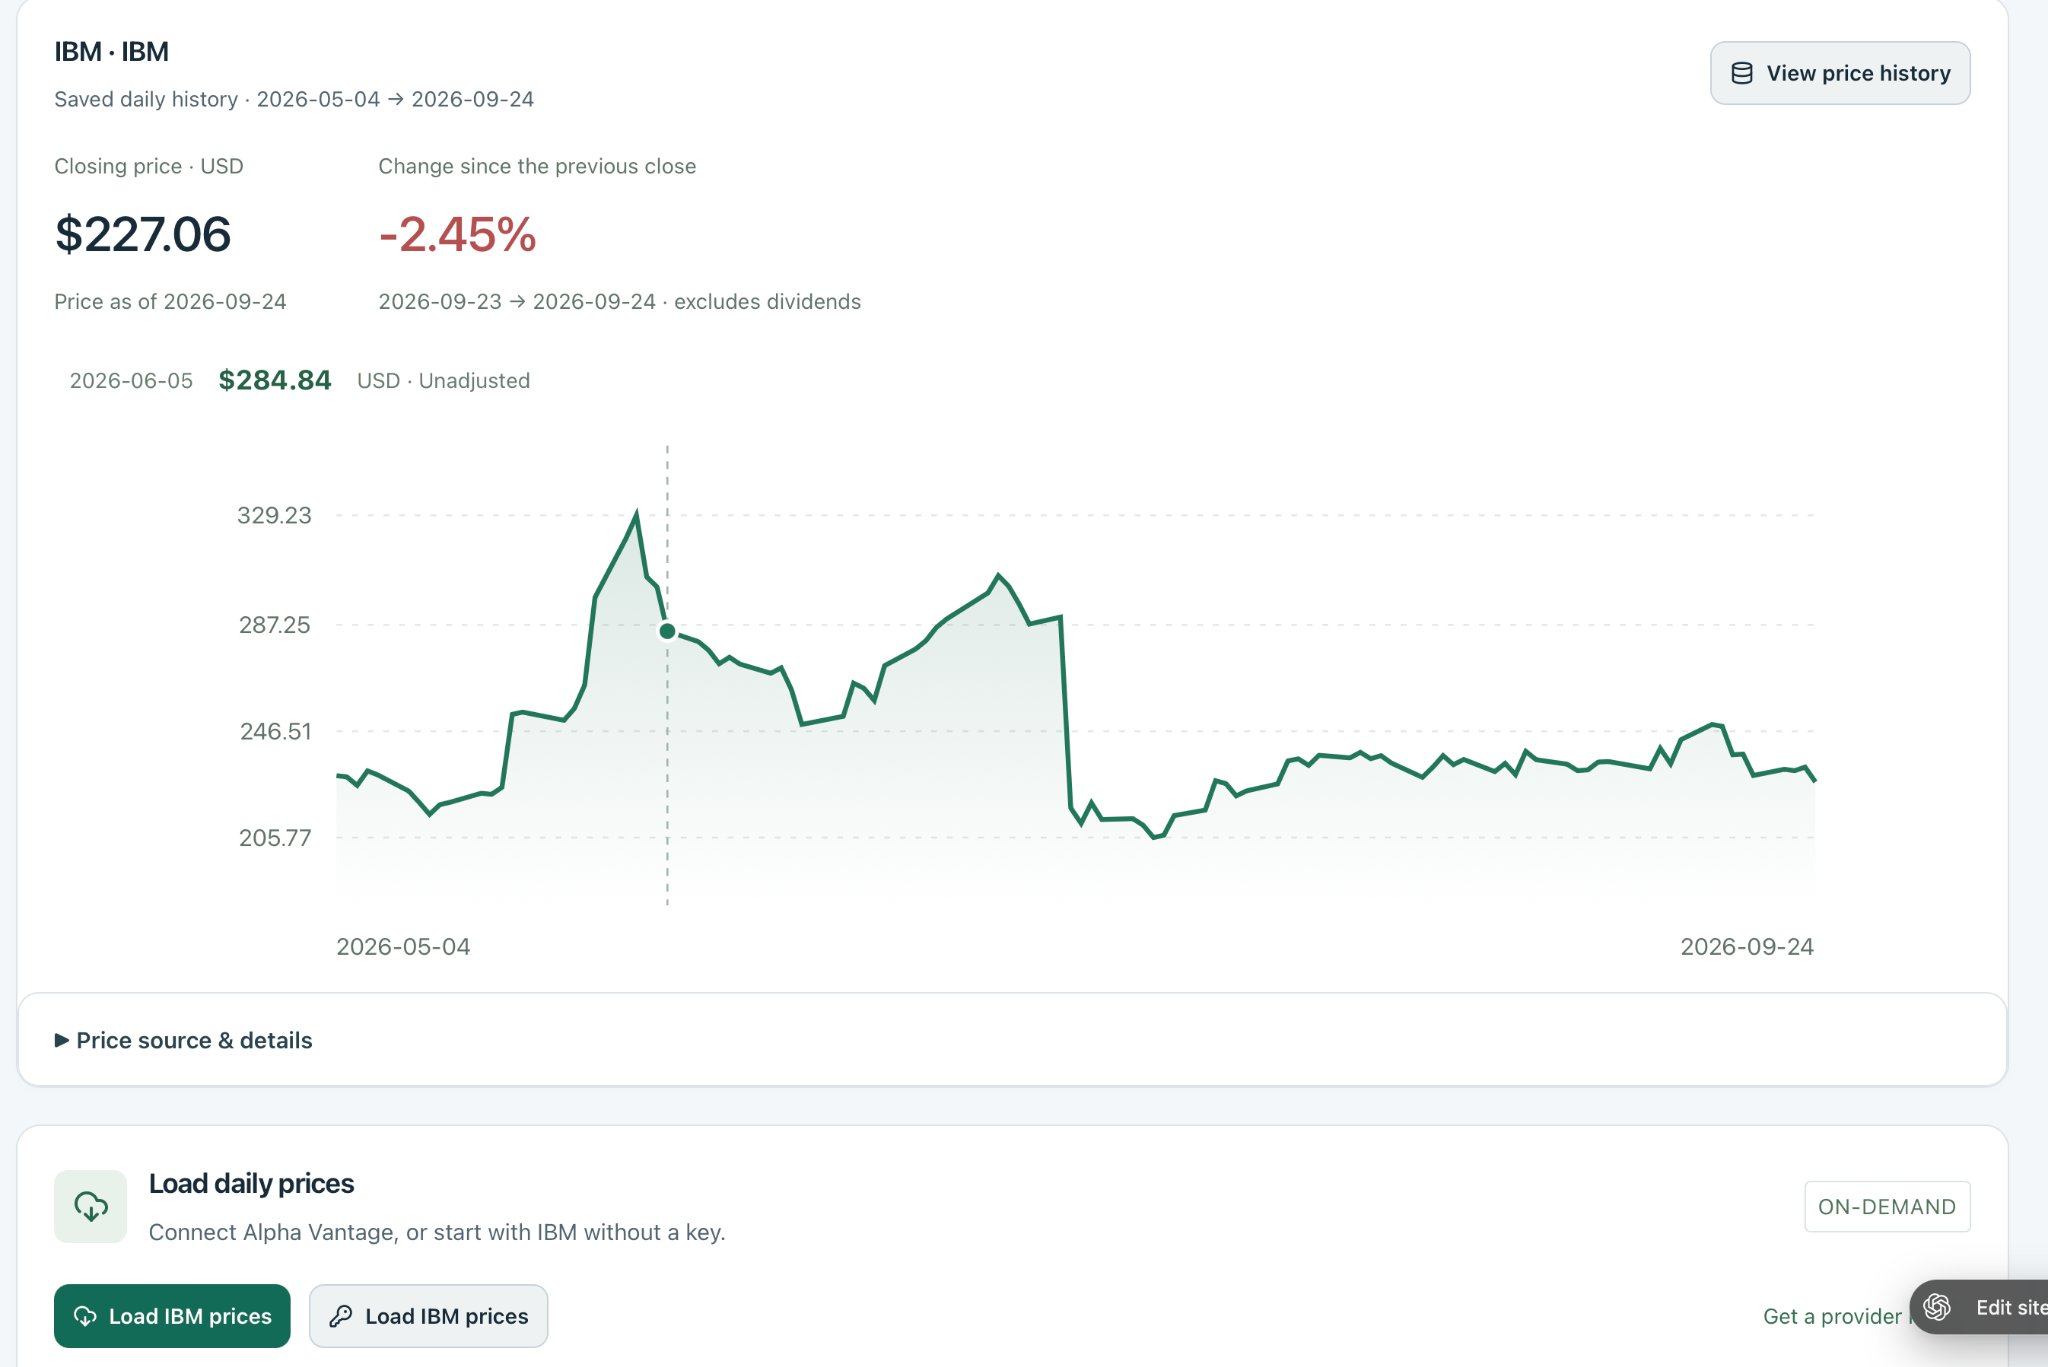
The stock-price image is a saved historical view, not a live quote. Backtests are research results, not forecasts.
MARKETLAB / SYSTEM OVERVIEW
The problem
A backtest is only useful when its data, accounting, execution assumptions, and saved result can be inspected. Background retries must not allow stale workers to overwrite a final result.
Engineering decisions
- Validated Alpha Vantage and CSV imports into owner-scoped immutable price snapshots with source provenance.
- Used exact cash/share arithmetic, causal next-close execution, frozen input identities, and inspectable saved backtests.
- Implemented authenticated, bounded Node/MongoDB workers with lease-token fencing and C++ risk checks.
- Added independent Python replay, report-bound receipts, and explicitly reviewed redacted sharing.
What the evidence shows
Three local runs completed 3,000 verified jobs at a combined 39.96 jobs/s and 319.77 ms client-observed p99. These describe one local workload, not production capacity. The hosted Workers/D1 application and separate research service retain distinct responsibilities.